What Is a Mortgage Rate Buydown? How North Shore Buyers Can Lower Their Monthly Payment
Sellers are offering rate buydowns as concessions in 2026. Here's how 2-1 buydowns and permanent buydowns work, what they cost, and whether you should ask for one.
Kathleen Militello
REALTOR®, eXp Realty · North Shore Coastal Homes & Living
If you're buying a home on the North Shore in 2026, you've probably noticed something: mortgage rates are high, inventory is rising, and sellers are getting creative to attract buyers. One of the most powerful tools in that toolkit is the mortgage rate buydown — and most buyers have never heard of it.
A rate buydown can lower your monthly payment by hundreds of dollars, make a home you thought was out of reach suddenly affordable, and cost the seller less than a price cut. But it only works if you know to ask for it. So let's break it down in plain English.
What Is a Mortgage Rate Buydown?
A mortgage rate buydown is a financing concession where someone — usually the seller — pays an upfront fee at closing to temporarily or permanently lower your mortgage interest rate. A lower rate means a lower monthly payment, which means more money in your pocket every month.
Think of it as the seller prepaying part of your interest. Instead of dropping their asking price by $10,000, the seller spends that $10,000 to buy down your rate — which can save you far more on a monthly basis than the price reduction would.
The Two Main Types of Rate Buydowns
1. Temporary Buydowns (2-1 or 3-2-1)
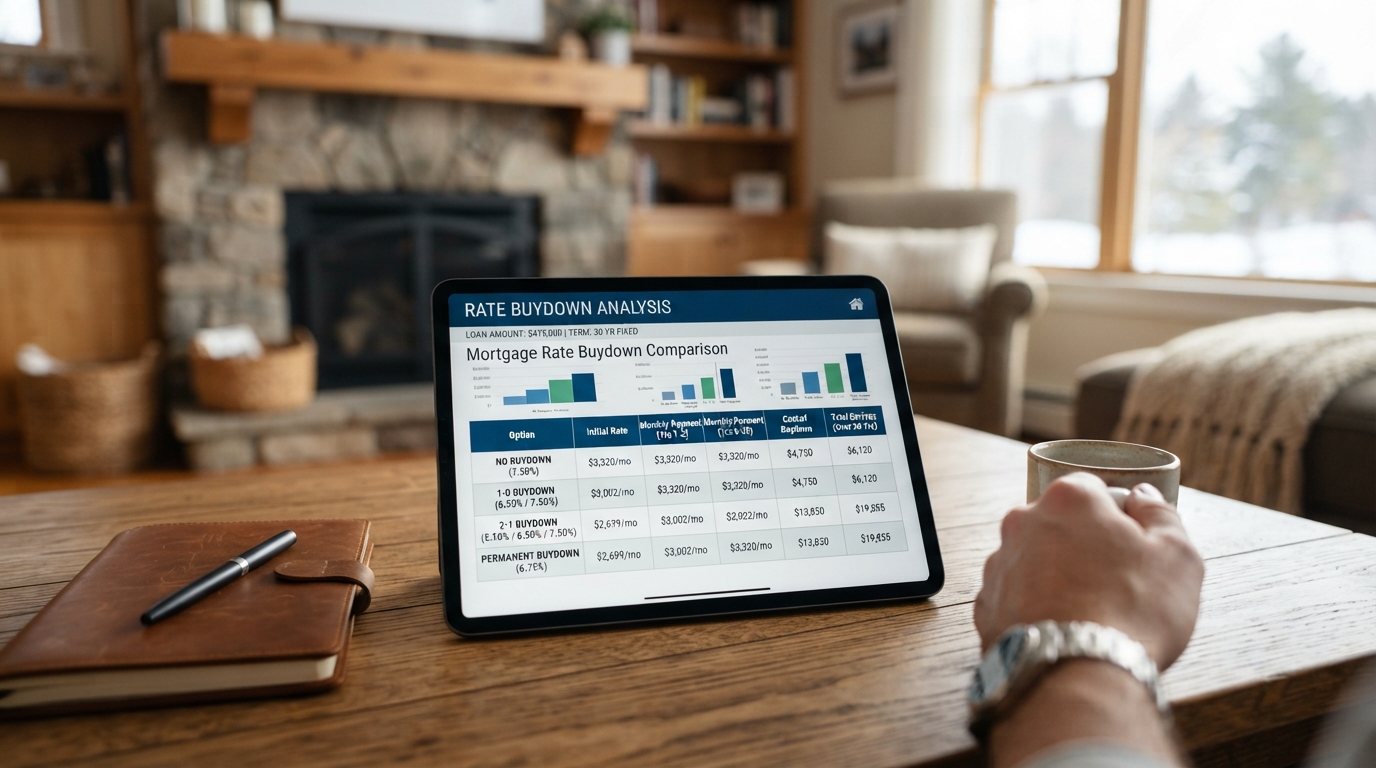
A 2-1 buydown is the most common type. It lowers your interest rate by 2 percentage points in year 1 and 1 percentage point in year 2. In year 3, your rate returns to the full note rate on your mortgage.
Here's an example on a $600,000 loan:
| Year | Note Rate | Buydown Rate | Monthly Payment | Monthly Savings |
|---|---|---|---|---|
| Year 1 | 6.5% | 4.5% | $3,040 | $783/mo |
| Year 2 | 6.5% | 5.5% | $3,404 | $419/mo |
| Year 3+ | 6.5% | 6.5% | $3,823 | — |
Example based on a $600,000 30-year fixed-rate loan. Actual rates and savings vary. Consult your lender for a personalized quote.
In year 1 alone, you save over $9,300. Over two years, the total savings exceed $14,000 — and the seller funded it all at closing through an escrow account. A 3-2-1 buydown works the same way but extends the savings over three years instead of two.
2. Permanent Buydowns
A permanent buydown lowers your interest rate for the entire life of the loan. This is essentially the same thing as paying discount points — you pay an upfront fee to buy a lower rate forever. The cost is typically 1% of the loan amount per 0.25% rate reduction.
On a $600,000 loan, buying the rate down 0.5% permanently costs about $12,000. That saves you roughly $200/month for 30 years — over $70,000 in total interest savings. The break-even point is usually 4 to 6 years. If you plan to stay longer than that, a permanent buydown pays for itself many times over.
Rate Buydown vs. Price Reduction: Which Is Better?
This is the question I get most often from North Shore buyers. The answer depends on your situation:
Rate Buydown Wins When:
- You need lower monthly payments to qualify or feel comfortable
- You plan to refinance if rates drop
- You want maximum cash flow in the first 1-2 years
- The seller offers it instead of a small price cut
Price Reduction Wins When:
- You plan to stay 10+ years and want maximum equity
- You're making a large down payment (20%+)
- You expect rates to stay flat or rise
- The price reduction is significant ($25,000+)
Here's the math that surprises most buyers: a $10,000 price reduction on a $600,000 home saves you about $60/month on a 30-year mortgage at 6.5%. That same $10,000 spent on a 2-1 buydown saves you $400–800/month in the first two years. The buydown delivers 5-10x more monthly relief — but only temporarily. If you need breathing room now, the buydown wins. If you're building long-term wealth, the price reduction wins.
How to Ask for a Rate Buydown in Your Offer
In the 2026 North Shore market, sellers are more willing than ever to offer concessions. Here's how to position a buydown in your offer:
- Request it as a seller concession. Instead of asking for a $10,000 price reduction, ask the seller to credit $10,000 toward a 2-1 rate buydown. Your lender will calculate the exact cost.
- Get quotes from your lender first. Before making the ask, have your lender run the numbers — how much a 2-1 buydown costs, what your payment looks like each year, and whether you qualify at the full note rate.
- Frame it as a win-win. The seller spends less than a price cut, you get lower payments, and the deal closes. It's a concession that costs the seller less and benefits you more.
- Combine with other terms. A buydown can be paired with a flexible closing date, an appraisal gap coverage clause, or a home sale contingency to make your offer more attractive.
What to Watch For
Rate buydowns are powerful, but they come with a few things to keep in mind:
- •You must qualify at the full note rate. Lenders verify that you can afford the payment at the original rate, not the buydown rate. The buydown is a bonus, not a qualification shortcut.
- •Temporary buydowns expire. Your payment will increase in year 2 or year 3. Budget for the full payment from day one so the increase doesn't surprise you.
- •Refinancing isn't guaranteed. If rates rise instead of fall, you can't refinance into a lower rate. The buydown gives you temporary relief, not a permanent solution.
- •Not every lender offers every program. Some lenders only offer 2-1 buydowns; others offer 3-2-1 or permanent options. Ask your lender what's available.
Why This Matters on the North Shore Right Now
The North Shore market in 2026 is different from the frenzy of 2021-2023. Inventory is up, days on market are longer, and sellers are motivated. That means buyers have leverage — and rate buydowns are one of the most effective ways to use it.
I'm seeing sellers in Beverly, Peabody, Danvers, and Haverhill offering buydowns to close deals. Even in tighter markets like Marblehead and Manchester-by-the-Sea, a well-structured offer that includes a buydown request can set you apart from competing buyers who only ask for price reductions.
The key is knowing the numbers before you make an offer. Talk to your lender, understand what a buydown costs and saves, and then let me help you structure the ask. This is exactly the kind of negotiation that can save you thousands over the life of your loan.
Want to See if a Rate Buydown Works for You?
I'll help you run the numbers, structure the offer, and negotiate with the seller. No pressure — just straight answers about what saves you money.
Or call (978) 500-1480Frequently Asked Questions
Kathleen Militello
REALTOR®, eXp Realty · North Shore Coastal Homes & Living
Kathleen has helped over 2,000 families buy and sell homes across the North Shore for 20+ years. She specializes in coastal communities, first-time buyers, and strategic negotiation. Her approach is simple: straight answers, deep local knowledge, and a commitment to getting you the best deal possible.