Buying Tips
Assumable Mortgages Explained: What Buyers and Sellers Need to Know
Kathleen Militello · Published October 16, 2026 · Updated October 16, 2026 · 8 min read
Buying Tips
Kathleen Militello · Published October 16, 2026 · Updated October 16, 2026 · 8 min read
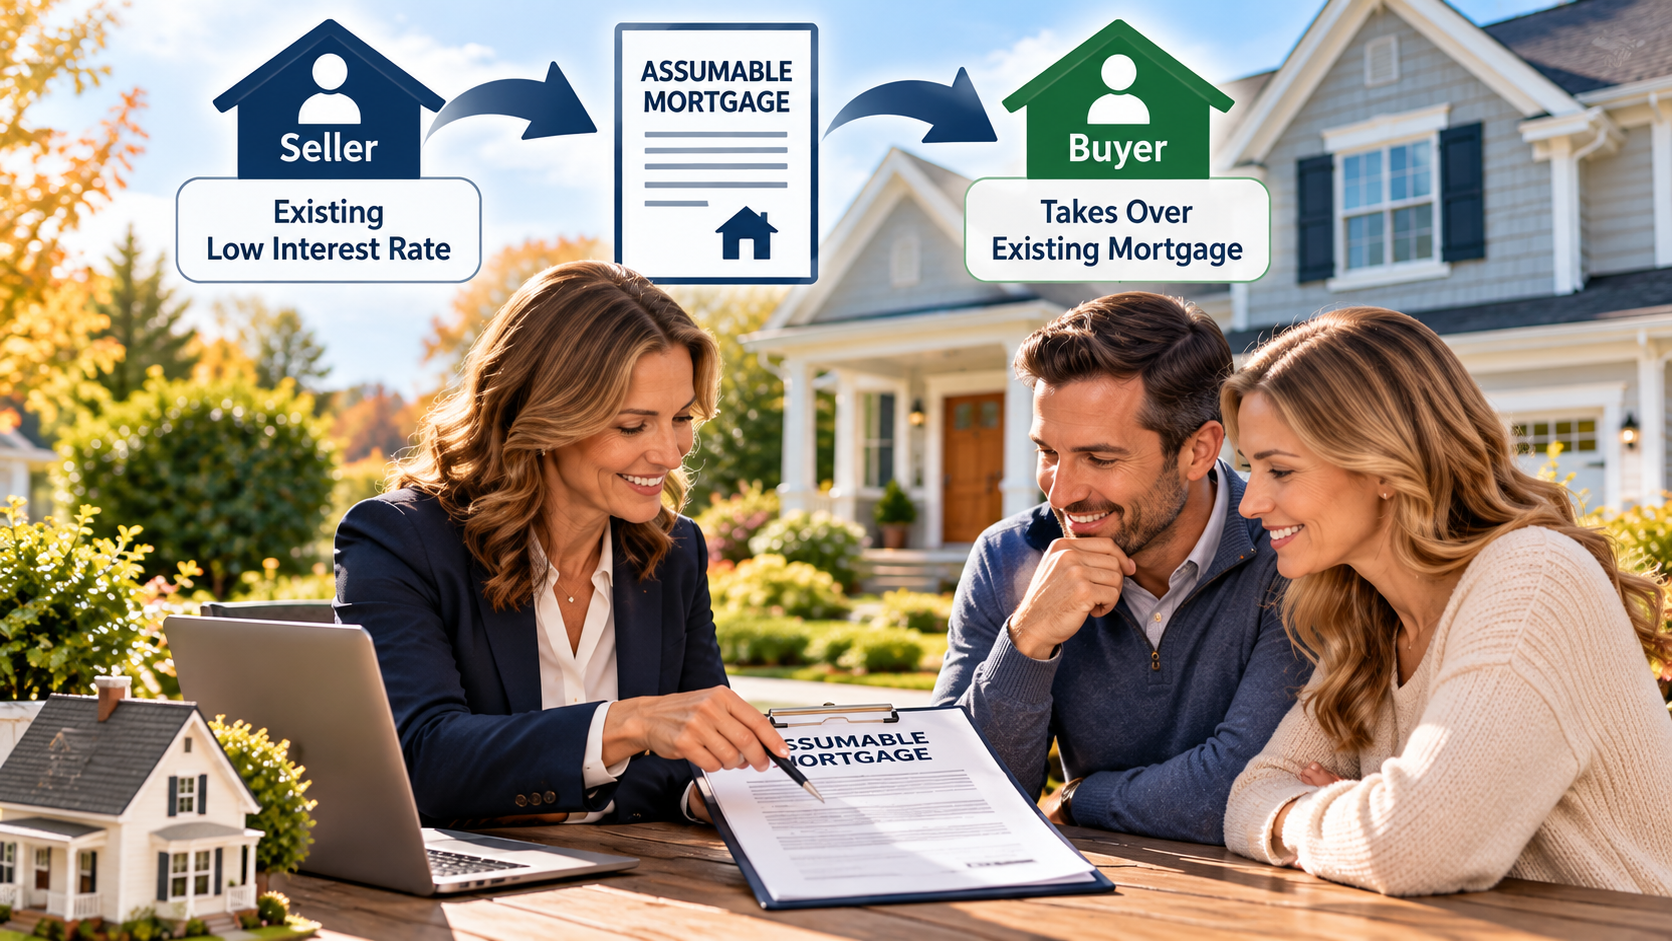
An assumable mortgage lets a buyer take over the seller's existing loan, including its interest rate, remaining balance, term, and monthly payment, instead of taking out a new mortgage. For a seller who locked in a lower rate, an assumable loan can be a genuine marketing advantage. For a buyer, it can mean a lower monthly payment and lower closing costs than a brand-new loan at today's rates.
Here is how it works, who can use it, and how to get started on the North Shore.
Key Takeaways
An assumable mortgage lets a buyer take over the seller's existing loan, including its interest rate, remaining balance, term, and monthly payment, instead of opening a new mortgage.
FHA, VA, and USDA loans are generally assumable with lender approval. Most conventional loans are not, because they carry a due-on-sale clause.
The buyer always has to qualify with the current loan servicer, and the biggest hurdle is usually the equity gap, the difference between the sale price and the seller's remaining balance.
A proper assumption with the lender's approval, sometimes called novation, is what releases the seller from liability, and the terms should always be in writing.
Kathleen can help sellers tell buyers about an assumable loan in the marketing, and help buyers evaluate whether assuming makes sense, always alongside their lender and attorney.
You take over the seller's loan, not a new one
An assumable mortgage lets a buyer step into the seller's existing loan exactly as it stands: the same interest rate, the same remaining balance, the same term, and the same monthly payment. Instead of shopping for a brand-new mortgage at today's rates, the buyer keeps the loan the seller already has.
For a seller who locked in a lower rate, that existing loan can be a powerful marketing point, because it gives buyers a path to a lower monthly payment than a new loan would offer. For a buyer, it can mean a lower monthly payment and lower closing costs than starting fresh, which is why assumptions have become one of the most talked-about tools on the North Shore.
Not every mortgage can be assumed
The short answer is that FHA, VA, and USDA loans are generally assumable, with the lender's approval. Those programs were built to be portable in a way that keeps the loan attached to the property, so a qualified buyer can step into it.
Most conventional loans, the ones backed by Fannie Mae and Freddie Mac that make up the bulk of the mortgage market, are not assumable. They contain a due-on-sale clause, which means the full balance becomes due when the property changes hands. If the loan is conventional, an assumption is usually off the table.
Eligibility depends on the loan type and the servicer
FHA loans are assumable if the buyer qualifies under standard FHA underwriting: credit, income, debt-to-income, and in most cases owner-occupancy. VA loans are assumable too, and the buyer does not need to be a veteran, but they do need to meet the lender's credit and income standards. For VA loans originated after March 1, 1988, VA approval is required, and a funding fee may apply for non-veterans.
USDA loans are assumable for buyers who meet USDA eligibility, including income limits based on where the property sits. In every case, the buyer has to qualify with the current loan servicer. That qualification step is non-negotiable, and it is where the fine print of the loan gets real.
The difference between price and balance
Here is where many assumptions stall. The buyer is not paying the seller's remaining balance; they are paying the full purchase price. The difference between the purchase price and the seller's remaining loan balance is called the equity gap, and the buyer has to cover it, usually in cash or with a second loan.
On a home that has appreciated, that gap can be substantial, and it is often the single biggest hurdle in an assumption. A buyer who cannot cover the gap in cash may be able to layer a second loan on top of the assumed first, but that means qualifying for two loans at once. It is a conversation worth having with a lender early. If your money is tied up in your current home, my answer to how to buy another house when your money is tied up walks through the options.
The path from listing to assumption
The first call is to the seller's loan servicer, the company that collects the payments. Ask directly whether the loan is assumable and what the process involves. The answer shapes everything that follows.
Look at the interest rate, the remaining balance, the term, and the monthly payment. These details tell you whether the loan is actually worth assuming compared with a new mortgage.
The servicer has a formal application process. Ask for it early, because it can take time, and the servicer sets the schedule.
The buyer goes through the servicer's underwriting: credit, income, assets, and debt. This is not a formality. It is a real qualification, and it decides whether the assumption can happen.
The buyer brings the difference between the purchase price and the seller's remaining balance, in cash or with a second loan arranged through their lender.
Once approved, the buyer signs the assumption agreement with the servicer. A proper assumption with the lender's approval, sometimes called novation, is what releases the seller from liability on the loan. Everyone should get the terms in writing.
Closings in Massachusetts require a real estate attorney, and an assumption is exactly the kind of transaction where legal review earns its keep. Your attorney and the buyer's attorney make sure the documents line up and your interests stay protected.
If you are wondering what happens at a Massachusetts closing, that page walks through the final stretch of any purchase, assumed loan or not.
What assuming actually gets you, and what it costs
Why buyers consider it
Why it is not automatic
Kathleen can help sellers tell buyers about an assumable loan right in the marketing, and help buyers evaluate whether assuming makes sense, always alongside their lender and attorney. Every home and every situation is different, and the right answer comes from the specific loan and the specific house.
Know the loan before you fall in love with the house
An assumable mortgage is not a magic trick. It is a specific loan feature that works when the loan is assumable, the buyer qualifies, the equity gap is manageable, and the rate is actually better than what a new loan would offer. When those line up, it can be a genuine advantage for both sides.
If you are selling, tell your listing story with the loan in it, and let Kathleen help you market an assumable loan to the right buyers. If you are buying, ask the question early, run it past your lender and your attorney, and get everything in writing before you count on it.
Every home and every loan is different, and no two assumptions look exactly alike. That is why the conversation starts with the specific numbers on your home or the home you want, never a general answer. If you are wondering whether an assumable loan fits your move, that is exactly the question Kathleen is good at working through, with no pressure and no jargon. Call or text her at 978-500-1480 or book a conversation, and you will look at your options together. Warmly, Kathleen Militello, Realtor®, eXp Realty.
Ask Kathleen
Straight answers to the questions assumptions keep bringing up, from the article above.
An assumable mortgage lets a buyer take over the seller's existing loan, including its interest rate, remaining balance, term, and monthly payment, instead of opening a new mortgage.
FHA, VA, and USDA loans are generally assumable with lender approval. Most conventional loans are not, because they contain a due-on-sale clause that makes the full balance due when the property changes hands.
No. The buyer does not need to be a veteran, but they must meet the lender's credit and income standards. For VA loans originated after March 1, 1988, VA approval is required, and a funding fee may apply for non-veterans.
The equity gap is the difference between the purchase price and the seller's remaining loan balance. The buyer has to cover it, usually in cash or with a second loan, and it is often the biggest hurdle in an assumption.
A proper assumption with the lender's approval, sometimes called novation, is what releases the seller from liability. Everyone should get the terms in writing.
Written by
Kathleen Militello, Realtor®
The Militello Team · AI Certified Agent™ · Certified Negotiation Specialist™ · eXp Realty
Kathleen Militello, Realtor® with eXp Realty, serving Boston's Coastal North Shore. Licensed since 2003 with over two decades on the ground, she helps buyers and sellers navigate the North Shore market with smart pricing, innovative marketing, and strong negotiation.
Keep your reading going
Every home and every loan is different. Kathleen can help sellers feature an assumable loan in their marketing and help buyers evaluate whether assuming makes sense, always alongside their lender and attorney. That conversation starts with your specific numbers, not a pitch.
Assumability, eligibility, and loan terms are set by the loan servicer and the loan program, and nothing here is a guarantee that a specific loan can be assumed. Confirm the details with the current loan servicer, your lender, and your attorney. Kathleen Militello is a Realtor® with eXp Realty, MA Salesperson License 9053343. All real estate services are offered in accordance with the Fair Housing Act and Equal Housing Opportunity.
Related Posts
From the page to the porch
A note can only tell you so much. Let Kathleen take you through the towns, the streets, and the options that actually fit.