1
Find Eligible Homes
We start with homes that participate in rent-to-own programs. Not every listing is available this way, so the first step is identifying eligible properties in the towns that interest you.
An alternative path to homeownership
An alternative path to homeownership on the North Shore. I help you understand how rent-to-own programs work and whether they may be the right fit for your situation.
Key Takeaways
Rent-to-own lets you rent a home now with the option, or the agreement, to buy it later, and part of what you pay can count toward the future purchase.
The two main structures are lease-option, where you have the right to buy, and lease-purchase, where you commit to buying at the end of the term.
The terms that matter most are the purchase price, the option period, the option fee, who handles maintenance, and who carries the taxes and insurance while you rent.
Rent-to-own is a written contract, and in Massachusetts that means every document should be reviewed by a real estate attorney before you sign.
Availability on Boston's Coastal North Shore varies town by town and property by property, so the best first step is a conversation about the towns you want and the timeline you need.
Every situation is different, and there is no pressure to decide anything today. Send me a question or book a conversation, and I will give you a straight answer about whether rent-to-own makes sense for your move.
The basics
Rent-to-own is a home purchase arrangement where you rent a home today with the option, or the agreement, to buy it at a later date. A portion of your rent, or an option fee paid up front, is often credited toward the future purchase. In plain terms, you live in the home first, build toward owning it, and complete the purchase when the agreed term arrives, usually within one to three years.
The structure exists for a simple reason: not everyone is ready for a traditional mortgage today, but plenty of buyers know exactly where they want to live. Rent-to-own can bridge that gap, giving you time to strengthen your credit, grow your savings, or wait for better financing terms while the home you love is held for you.
It is not the same as buying, and it is not the same as renting. It sits between the two, and it only works well when you understand the terms before you sign.
How it works
Rent-to-own programs can provide a bridge to homeownership for those who may not be ready for a traditional mortgage today but want to secure a home for the future.
These programs typically involve renting a home with the option or agreement to purchase it at a later date. I can guide you through the different program structures, qualification requirements, and North Shore availability.
We start with homes that participate in rent-to-own programs. Not every listing is available this way, so the first step is identifying eligible properties in the towns that interest you.
You and the seller agree on the purchase price, the option period, the option fee, the monthly rent, and how much of each payment counts toward the eventual purchase.
The arrangement is written into a lease-option or lease-purchase agreement. In Massachusetts, your real estate attorney reviews this contract before anyone signs.
You move in and rent for the agreed term, using the time to build credit, save for a down payment, or secure mortgage financing.
When the term ends, you exercise your option to buy at the agreed price, or you complete the purchase you committed to, and the home becomes yours.
Why people consider it
Lock in your future home while you prepare for a traditional mortgage.
Select from eligible homes on the market that fit the program criteria.
Understand the terms, timelines, and costs before you move forward.
Program structures
Not every rent-to-own arrangement works the same way. The three main structures differ in how much you commit, and the difference matters.
You rent the home with the option to buy it at a set price within a set window, usually one to three years. The option is yours: if the timing is not right at the end, you can walk away, though you typically forfeit the option fee. This structure gives the most flexibility.
You commit to buying the home at the end of the term. The sale price and closing date are set up front, and a portion of your rent can count toward the purchase. Because you are committed, the terms are firmer, and you are expected to complete the purchase.
In some cases the owner acts as the lender instead of a bank. You pay the seller directly over the agreed schedule, and the deed transfers once the terms are met. These arrangements are highly customized and need especially careful review, because Massachusetts real estate purchases carry specific legal requirements.
There is no single document for all of this, which is why the written agreement for your specific home is the only thing that counts.
Due diligence
Rent-to-own can be a genuine path to homeownership, and it can also hide costs when the terms are not clear. These are the details I look at with every client:
The option fee is the money you pay for the right to buy later. It is usually non-refundable, so understand what happens to it if you do not complete the purchase.
Is the future price locked on day one, or tied to an appraisal at the end of the term? Know which one your agreement uses, because it changes your whole financial picture.
Who fixes the roof, the furnace, or the leaky faucet while you rent? Some agreements shift major repair costs to the tenant-buyer. That should be spelled out in writing before you move in.
Property taxes and homeowners insurance are real costs during the rental period. The agreement must say who carries them, and some programs require the property to stay insured throughout the term.
In Massachusetts, a real estate attorney should review every contract before you sign. This is not a formality, it is the best protection you can buy, and I will help you find one.
Massachusetts & the North Shore
Massachusetts does not run a single state-level rent-to-own program, so arrangements are created by individual sellers, investors, and private programs.
Because rent-to-own is a contract for a future deed transfer, the paperwork often touches on title, taxation, and local property rules that a standard lease never reaches.
Salesperson representation rules still apply: I act in your interest, and every offer and agreement goes through the same local practice as a traditional sale.
Availability follows the market: some coastal sellers list a home as a lease-option for steady rental income and a future sale, while others use the structure to reach buyers who cannot qualify for financing today.
Because Massachusetts does not run a state rent-to-own program, availability is created home by home. On Boston's Coastal North Shore, the towns where eligible properties appear tend to follow the local market, and the terms differ with every owner. My job is to find out what is actually available in the communities you care about:
The fit
The structure helps some buyers and is a poor fit for others. Here is an honest look at both sides.
The right answer for you comes from your numbers, your timeline, and your comfort with the terms, not from a generic rule.
Questions, answered
Real questions I hear from North Shore buyers considering this path.
Standard renting gives you a place to live and nothing else. Rent-to-own adds the right, or the commitment, to buy the home later, and part of what you pay can count toward the purchase. That future claim on the home is the difference.
Not in the traditional mortgage sense, but you will typically pay an option fee up front, and some programs expect a small deposit beyond the first month's rent. The exact amount is set in the agreement, and I will lay out the full numbers before you commit to anything.
In a lease-option, you can walk away when the option expires, though you generally forfeit the option fee and any rent credits. In a lease-purchase, you have agreed to buy, and backing out can carry legal and financial consequences. The two structures behave very differently, which is why we read the contract together before anyone signs.
Only homes whose owners agree to the structure. In practice it depends on the seller: some list a property as a lease-option or lease-purchase, while others sell only in the traditional way. I track the programs and properties that are actually available on the North Shore.
It depends entirely on the agreement. Some keep the owner responsible for the major systems, while others shift repairs to the tenant-buyer because you are the future owner. Never assume, and never sign until that paragraph is clear.
Rent-to-own fits best when you are confident about the town you want, comfortable with the fees, and able to see yourself completing the purchase within the term. A conversation about your timeline, credit, and budget will tell us whether the structure helps you or just adds cost. That is exactly what I am here for.
Next step
I am here to help you navigate all paths to homeownership on the North Shore.
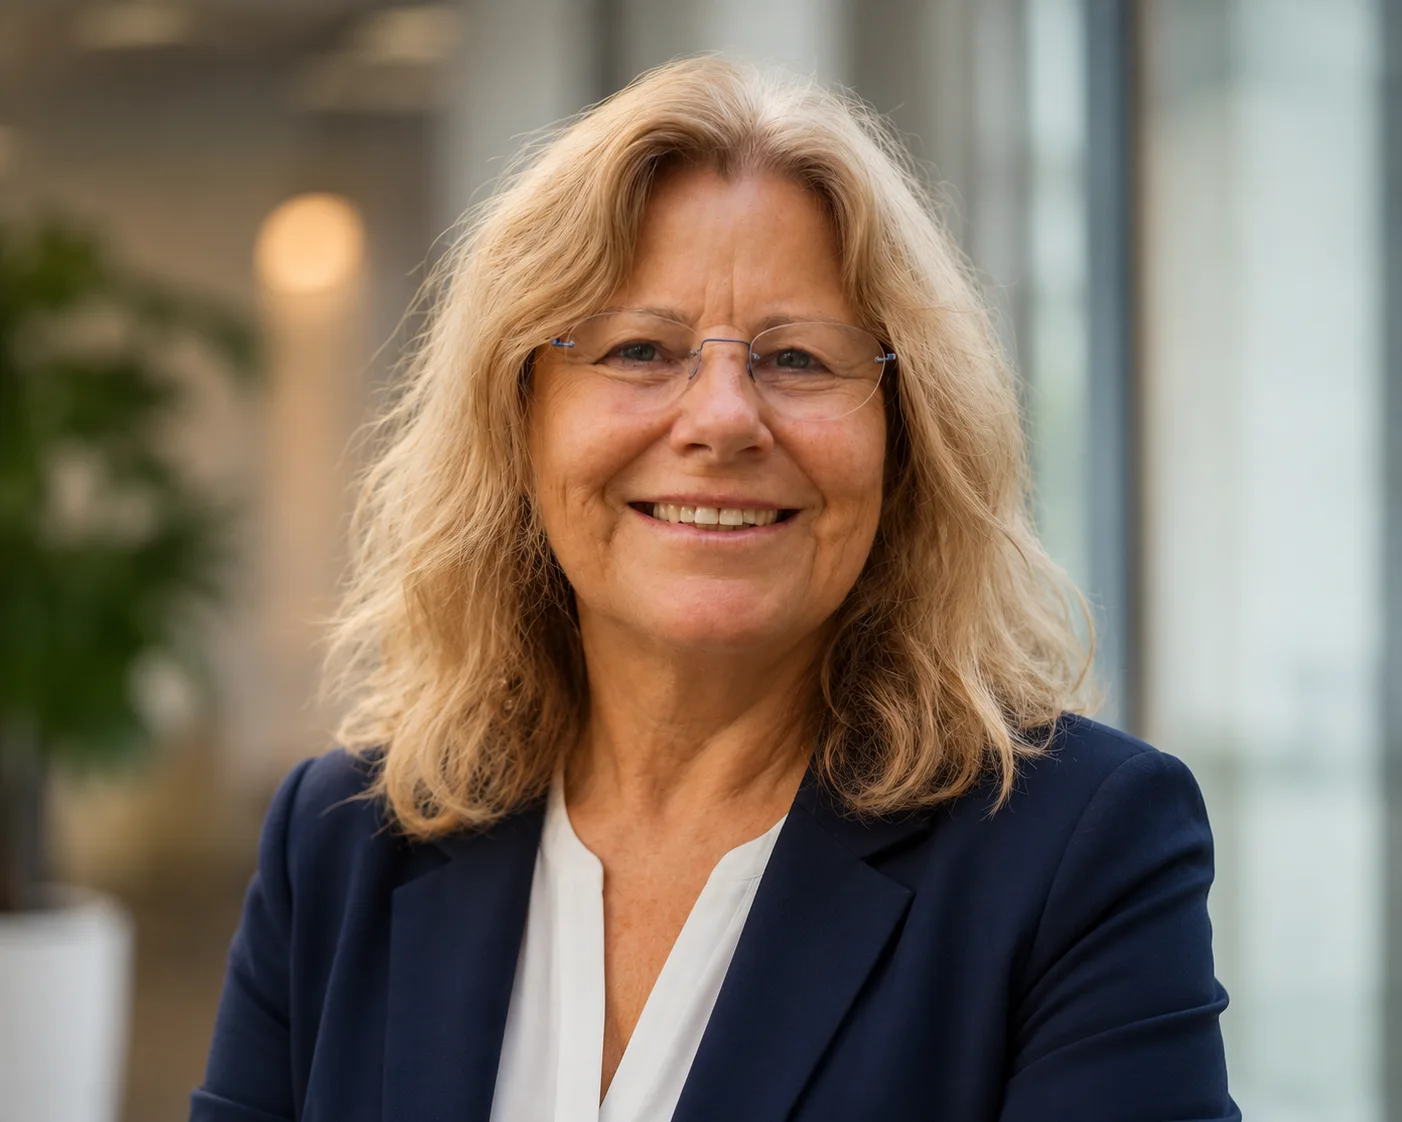
Meet Kathleen
The Militello Team · eXp Realty
Licensed in Massachusetts since 2003 and working in real estate full time since 2007, I have spent more than two decades helping buyers and sellers across Boston's Coastal North Shore. As an AI Certified Agent and Certified Negotiation Specialist with eXp Realty, I bring modern tools, deep local market knowledge, and patient guidance to every path toward homeownership, including the less traditional ones.
I listen first, ask questions, and tell people what I really think. When you are weighing rent-to-own against other options, you get a straight answer about the costs, the risks, and whether the path honestly serves your move.
Because in real estate, Experience Matters.
Request program details
Rent-to-own is one path, not the only path. Tell me where you want to live on the North Shore and where your finances stand today, and I will walk you through the options that honestly fit: rent-to-own, traditional buying, or a plan to get ready for one. You don't have to figure this out alone.
Warmly, Kathleen
Kathleen Militello is a licensed Massachusetts real estate salesperson (License 9053343) affiliated with eXp Realty. This page is for general information only and is not legal, tax, or financial advice. Rent-to-own terms vary by property, owner, and program, and Massachusetts purchase and lease arrangements carry specific legal requirements. Review any rent-to-own agreement with your own attorney before signing. Equal Housing Opportunity.