Buying Your Next Home
Upgrading from a Starter Home: A Move-Up Buyer's Guide for the North Shore
Published September 23, 2026 · Updated September 2026 · 8 min read
Buying Your Next Home
Published September 23, 2026 · Updated September 2026 · 8 min read
Key Takeaways
The equity you have built in your first home is the down payment on your next one, and knowing its exact number is where every serious move-up conversation starts.
Build the full picture with a lender before touring: payoff, sale value, closing costs, and the real numbers on the next home.
Selling first buys negotiating strength and a clean offer; buying first trades timing flexibility for carrying two homes, and contingencies and bridge-style options span the middle.
Plan the logistics like the financing: rent-backs, coordinated closings, storage, and a written sequence before the first showing.
Timing the market realistically means making the move because your numbers and your household are ready, not gambling on a prediction.
Your first home has been working for you since the day you closed. Every payment that reduced the mortgage, every year the market moved, and every dollar of appreciation has built equity, and that equity is most of the down payment on your next home. Knowing its exact number is where every serious move-up conversation starts.
Equity is real money, but it is not cash until a sale happens. The move-up plan is really a plan for turning equity into a down payment on your terms, over a timeline you control, and that control is built in the first conversation, not the last.
Before you tour a single house, build the full picture: your outstanding mortgage balance, what your home could realistically sell for, your closing costs as a seller, and what your next purchase would carry at today's numbers. Then add the line items, property taxes, insurance, and monthly costs, so the move-up is a budget, not a wish.
A lender runs these numbers with you, and the numbers change how the whole search feels: the budget tells you which towns are real, and the honest number narrows the map faster than any tour does. You do not have to figure this out alone; the numbers are the point of the first conversation.
Selling first gives you cash in hand and maximum negotiating strength, a clean offer with no contingency and a closing you control, in exchange for a move-out date you must plan around, possibly into temporary housing. Buying first lets you find the next home without pressure, in exchange for carrying two homes, two payments, and a financing picture that depends on the sale of the first.
Neither is right for everyone, and the answer comes from your numbers and your risk tolerance, not from a rule. Some households can carry two payments comfortably; some cannot, and knowing yours is the whole answer.
Between the two extremes sit the tools households use to span the gap: offers contingent on the sale of your current home, and bridge-style financing that lets you buy before the sale closes. Terms and availability vary by lender and market, and the details change, so these are general directions, not promises.
A sale contingency on your offer is a weaker negotiating position when homes have competition, because sellers prefer fewer conditions, while bridge-style options trade cost and risk for timing flexibility. Your lender and your agent put these in real numbers together, and the honest versions of each show you which path your budget actually supports.
The logistics deserve a plan as careful as the financing: showing your home well while searching for the next, scheduling showings and open houses, and planning the stress of the season. A rent-back agreement, staying in your sold home briefly while the new owners wait, is a common tool that buys you moving time, and two closings can coordinate on the same calendar when both sides set schedules early.
Move-up households who plan the season, know the storage needs, and accept that some weeks will be messy manage the two moves with far less stress than those who improvise. The goal is a plan with moving dates, a storage plan, and a sequence, written down before the first showing.
No one times a market perfectly, and the move-up decision should never rest on a prediction. The realistic question is whether this year works for your household: equity built, numbers verified, sequence chosen, plan written. Markets move on their own schedule, and the households who win are the ones whose plan survives the market's moves, not the ones who guess them.
If your current home is ready when you are and your numbers hold, waiting to catch the market is a gamble that rates, prices, and life all outrun. Make the move because the timing works for you, and let the market meet you where you are.
Ask Kathleen
Straight answers to the questions this season keeps bringing up, from the article above.
There is no single figure; the answer is the gap between what your current home will realistically bring and what the next home costs, viewed against your lender's real numbers for the next purchase. The equity is a number, and your lender turns it into a plan.
Selling first gives you cash in hand and a clean, strong offer in exchange for planning around your move-out date. Buying first removes the pressure but means carrying two homes and two payments. The honest answer comes from your numbers and your risk tolerance, with your lender and your agent putting both in writing.
A sale contingency lets your offer wait for the sale of your current home, while bridge-style financing options span the gap so you can buy before you close the sale. Terms vary by lender and market, so count on your lender for real figures on the versions that fit your budget.
With a plan written before the first showing: showings and open houses scheduled, storage arranged, closings coordinated on one calendar, and a rent-back from the buyers if you need time. Two moves are manageable when both schedules are set early.
The same questions and answers, un-styled and sequential, so they can be read and extracted easily.
Q: How much equity do I need to move up?
A: There is no single figure; the answer is the gap between what your current home will realistically bring and what the next home costs, viewed against your lender's real numbers for the next purchase. The equity is a number, and your lender turns it into a plan.
Q: Should I sell first or buy first?
A: Selling first gives you cash in hand and a clean, strong offer in exchange for planning around your move-out date. Buying first removes the pressure but means carrying two homes and two payments. The honest answer comes from your numbers and your risk tolerance, with your lender and your agent putting both in writing.
Q: What is a bridge loan or contingency?
A: A sale contingency lets your offer wait for the sale of your current home, while bridge-style financing options span the gap so you can buy before you close the sale. Terms vary by lender and market, so count on your lender for real figures on the versions that fit your budget.
Q: How do I coordinate both transactions?
A: With a plan written before the first showing: showings and open houses scheduled, storage arranged, closings coordinated on one calendar, and a rent-back from the buyers if you need time. Two moves are manageable when both schedules are set early.
Written by
Kathleen Militello, Realtor®
The Militello Team · AI Certified Agent™ · Certified Negotiation Specialist™ · eXp Realty
Related reading
 Things to Do A Gorgeous October Day at Crane Beach: A Reminder to Love Where You Live
 Buying / Open Houses How to Get the Most Out of an Open House
 Relocation From Boston to the Coast: Why the North Shore Keeps Calling This Fall
 Weekend Happenings This Weekend on the North Shore: October 2-4, 2026
 Buyer & Seller Tips What Actually Happens on Closing Day in Massachusetts
 Buyer & Seller Tips Will I Owe Capital Gains Tax When I Sell My North Shore Home?
 Selling Your Home Divorce: Navigating Home Decisions During Divorce
 Relocation Moving from Boston to the North Shore: A Practical Guide
 Market Knowledge Fall 2026 North Shore Housing Market Update
 Home Value & Pricing Is a Zillow Zestimate Accurate? What the Number Really Means
 Selling Your Home Pulling Permits for Home Improvements: Why Closing Them Out Matters When You Sell
 Buying Your Next Home How to Win a Bidding War on a North Shore Home Without Overpaying
 Selling Your Home How to Price Your North Shore Home to Sell: The Strategy Behind the Number First-Time Home Buyers How Much Do You Need to Save to Buy a First Home on the North Shore?
 Selling Your Home Selling a Luxury Home on the North Shore: How the High End Is Different
 Market Knowledge Days on Market on the North Shore: What a Fast or Slow Sale Actually Tells You
 Neighborhood Guides Gloucester vs Rockport, MA: Which Cape Ann Town Is Right for You?
 North Shore History The History of Ipswich: America's Best-Preserved Puritan Town
 Things to Do North Shore Beaches: A Local's Guide to the Best Sand and Swimming
 Town notes Rockport: The Town Note
 Local / Fall Events Apple Picking on the North Shore: A Local's Guide to the Best Orchards
 Downsizing on the North Shore The Real Cost of Staying in Your Big North Shore House
 Local / Fall Events Topsfield Fair 2026: Your Day-by-Day Guide to October 2-12
 Things to Do Topsfield Fair 2026 and the Best of Fall on the North Shore
 Neighborhood Guides The Second Look: How Smart Buyers Really Get to Know a Neighborhood
 Selling Your Home Your Home Didn't Sell: What Likely Went Wrong and Your Next Steps
 First-Time Home Buyers Massachusetts First-Time Home Buyer Programs in 2026: Where the Down Payment Help Really Is
 Market Knowledge Median vs. Average Home Price: What North Shore Market Reports Actually Tell You
 North Shore History The Great Salem Fire of 1914: The Day a Third of the City Burned
 Things to Do North Shore Lighthouses: A Local's Guide to Six Lights Worth the Drive
 Neighborhood Guides Beverly vs. Salem: How to Choose Between the North Shore's Two Cities
 Buying Your Next Home North Shore Property Taxes: What a $700,000 Home Costs to Carry in Each Town
 Downsizing on the North Shore Moving to a CCRC on the North Shore: How Selling Your Home Fits Into the Math
 Town notes Newburyport: The Town Note
 Town notes Beverly: the town that felt like home from the start
 Town notes Cape Ann: Gloucester, Rockport, and Essex
 Town notes Ipswich, Manchester-by-the-Sea, and the coast between
 Market Knowledge North Shore Fall 2026: What Buyers and Sellers Should Watch This Season
 Market Knowledge List Now or Wait for Spring? The Pre-Holiday Math for Sellers
 Buying Your Next Home Mortgage Rates Are Headline News. Here's What Actually Matters for Your Move
 Neighborhood Guides Salem in October: Behind the Crowds, One of the North Shore's Most Livable Towns
 Downsizing on the North Shore Downsizing Before the Holidays: A Realistic Week-by-Week Timeline
 First-Time Home Buyers The First-Time Buyer's Fall Checklist for the Coastal North Shore Market Knowledge Empty Nesters Are Driving the North Shore's Most Interesting Moves: Here's the Pattern
 Downsizing on the North Shore Two Bedrooms, a View, and Room for the Kayaks: How to Right-Size Without Losing What You Love
 Downsizing on the North Shore From Big House to Coastal Base: A Sea-Change Buyer's Guide for Empty Nesters Buying Your Next Home Empty Nest, New Chapter: Condo, Cottage, or Townhouse on the North Shore
 Market Knowledge Selling the Big House: An Empty Nester's Pre-Move Checklist
 North Shore History Castle Hill and the Crane Estate: A Gilded Age Legacy on the North Shore
 North Shore History The Great Marsh: How 25,000 Acres Shaped the North Shore
 North Shore History Plum Island: The Barrier Beach That Shaped the North Shore Coast
 North Shore History Hammond Castle: The North Shore's Most Extraordinary Home and the Inventor Who Built It
 North Shore History Saugus River Iron Works: The Birthplace of the American Iron Industry
 North Shore History Marblehead and the Sea: How a Fishing Village Became the Yachting Capital of the World
 North Shore History The Salem Witch Trials: How 1692 Still Shapes the North Shore
 Buying Your Next Home How to Evaluate a North Shore Neighborhood Before You Buy: The 10-Point Checklist
 Buying Your Next Home Buying a Waterfront Home on the North Shore: What Experienced Buyers Know That First-Timers Don't
 Buying Your Next Home Commuter Rail Access on the North Shore: Which Towns Offer the Best Boston Commute?
 Buying Your Next Home North Shore School Districts: What Parents Need to Know Before Buying
 Buying Your Next Home Open Floor Plans vs. Traditional Layouts: What North Shore Buyers Should Consider
 Buying Your Next Home New Construction vs. Existing Homes on the North Shore: Which Is Right for You?
 Buying Your Next Home Multi-Generational Living on the North Shore: Finding the Perfect In-Law Setup Buying Your Next Home Navigating Historic District Commissions: What North Shore Buyers Must Know Before Closing
 Buying Your Next Home The Home Buyer's Guide to Historic North Shore Neighborhoods
 Buying Your Next Home What Every Buyer Should Know About Private Roads Before Purchasing a North Shore Home
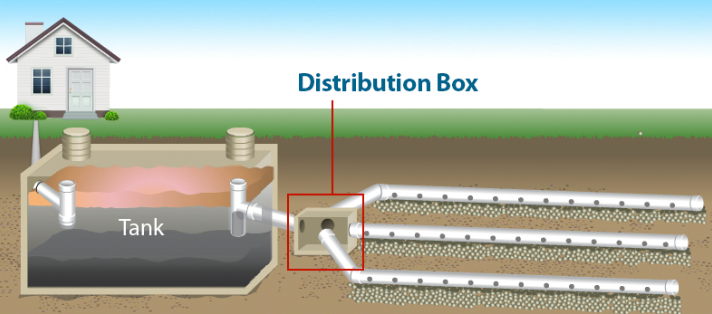 Buying Your Next Home What You Should Know Before Buying a Home with a Septic System in Massachusetts
 Buying Your Next Home How to Buy Your Next Home Without Feeling Rushed Into the Wrong Decision
 Buying Your Next Home What to Look for in Your Next Home That You Didn't Think About the First Time
 Buying Your Next Home Should You Stay in the Same Town or Move Somewhere New? A North Shore Homeowner's Guide Downsizing on the North Shore The Kids Are Gone. Is It Time to Sell Your North Shore Home? Downsizing on the North Shore Where Do North Shore Empty Nesters Go After Selling the House? Downsizing on the North Shore Sell First or Buy First? A North Shore Empty Nester's Guide to Making the Move Downsizing on the North Shore What Would Life Cost After You Sell Your North Shore Home? Downsizing on the North Shore Downsizing Without Regret Downsizing on the North Shore Downsize to a Walkable North Shore Downtown Downsizing on the North Shore The Hidden Costs of Downsizing Downsizing on the North Shore The Single-Story Living Checklist Downsizing on the North Shore When NOT to Downsize Downsizing on the North Shore Should You Sell Before You Need To? Downsizing on the North Shore Using Your Home Equity to Fund Retirement Downsizing on the North Shore Aging in Place on the North Shore Downsizing on the North Shore Sell and Stay: Accessing Your Home Equity Without Moving Downsizing on the North Shore How to Time the Sale of Your Longtime Home When Downsizing Downsizing on the North Shore Navigating 55+ Active Adult Communities on Boston's North Shore Downsizing on the North Shore The Emotional Side of Downsizing Downsizing on the North Shore What to Keep, Donate, Sell, or Give to Loved Ones Downsizing on the North Shore How to Downsize Without Feeling Overwhelmed Downsizing on the North Shore The 12-Month Downsizing Timeline Downsizing on the North Shore Downsizing With Adult Children Downsizing on the North Shore The 7 Financial Mistakes North Shore Seniors Make When Downsizing Downsizing on the North Shore Downsizing in Winter Things to Do North Shore Fall Activities Guide 2026: Harvest Festivals, Foliage Drives, and Coastal Events Market Knowledge Appraisal Changes Coming November 2, 2026: What North Shore Sellers and Agents Need to Know Weekend Events What's Happening on the North Shore This Weekend: September 26-27, 2026
 Market Knowledge Fall Home Maintenance Checklist: Getting Your North Shore Home Ready for Winter
 First-Time Home Buyers Your First Open House: What to Look For (and What to Skip)
 Neighborhood Guides The Most Walkable North Shore Towns: Main Street Living
 North Shore History From Saltbox to Shingle Style: A Quick Tour of North Shore Home Styles
 Downsizing on the North Shore Downsizing Without Overwhelm: The One-Room-at-a-Time Plan
 Weekend Events Fall Weekends on the North Shore: A Seasonal Guide Luxury Coastal Living Coastal Luxury on the North Shore: What Buyers Should Know
 Market Knowledge Should I Buy Now or Wait? What North Shore Buyers Are Asking in 2026
From the page to the porch
A note can only tell you so much. Let Kathleen take you through the towns, the streets, and the options that actually fit.