Ask Kathleen · Downsizing on the North Shore
The True Cost of Staying Versus Moving
Kathleen Militello, Realtor® · Published October 25, 2026 · Updated October 2026 · 8 min read · Boston's Coastal North Shore
Ask Kathleen · Downsizing on the North Shore
Kathleen Militello, Realtor® · Published October 25, 2026 · Updated October 2026 · 8 min read · Boston's Coastal North Shore
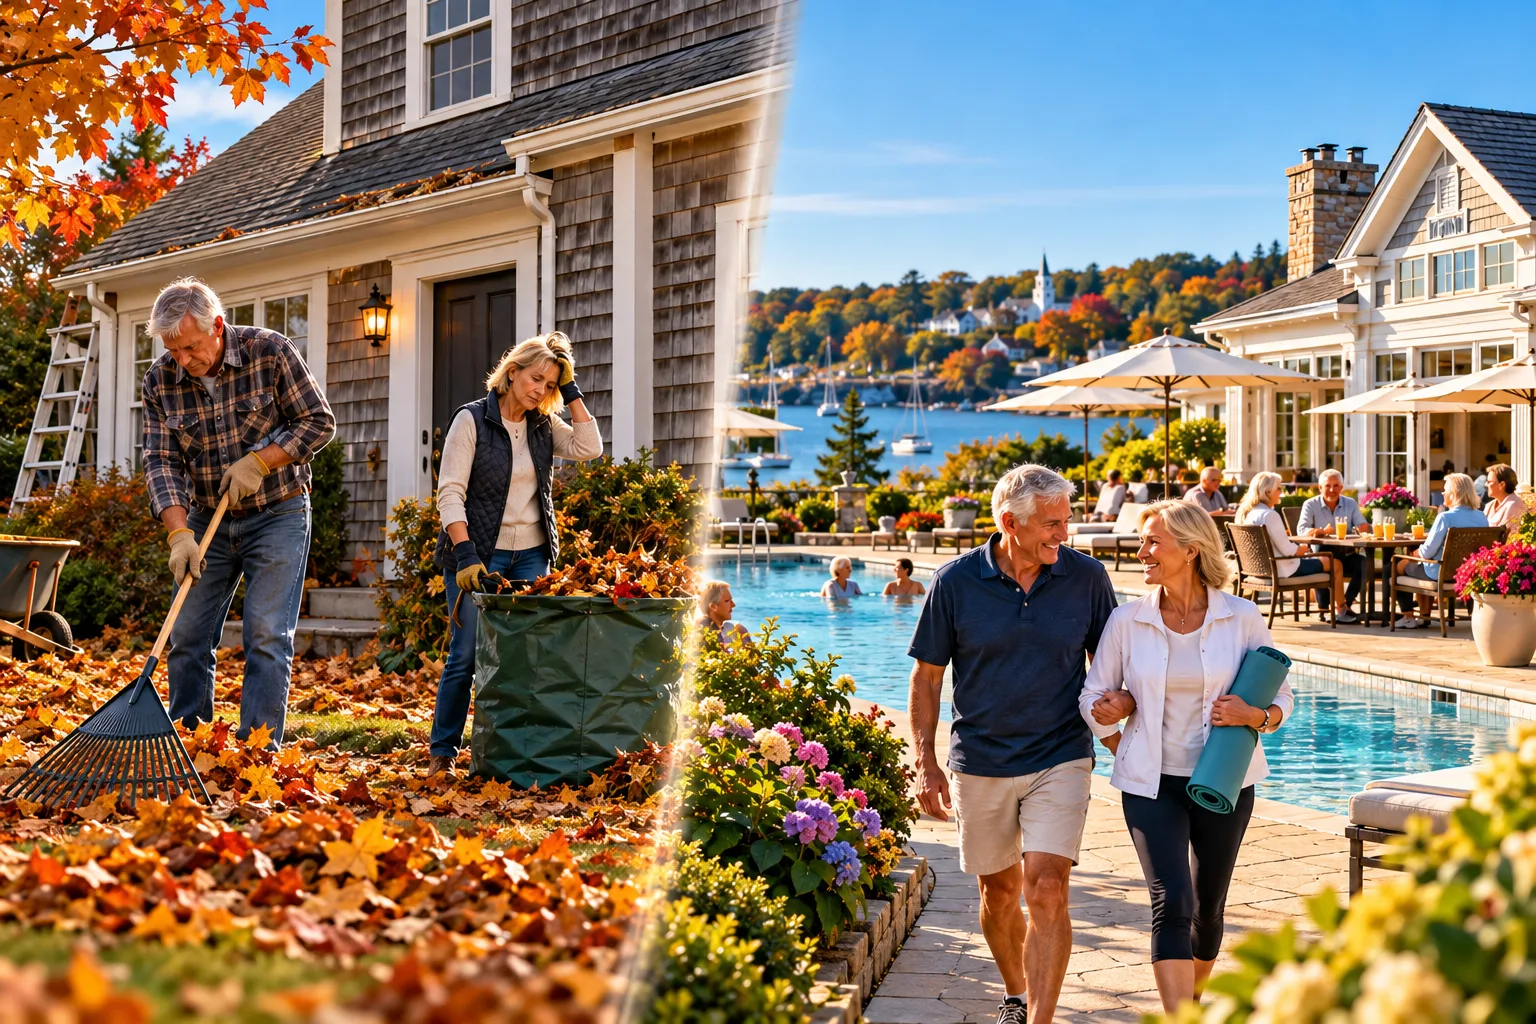
For a lot of North Shore homeowners, the question sounds simple: is it really more affordable to stay in the house we know, or does moving to something smaller actually cost less over time? The honest answer is that it depends, and finding it means doing the full math on both sides instead of trusting the side that feels safer. This is the conversation I have all the time at listing appointments and consultations, so let's walk through it together.
A move looks different once you see the full cost of selling. In Massachusetts, the total cost to sell a home commonly lands around 9 to 11 percent of the sale price once everything is counted. Real estate commission typically runs 5 to 6 percent of the sale price, and it is negotiable. The state deed excise tax adds $4.56 per $1,000 of sale price, a real estate attorney is required at every Massachusetts closing, and staging and pre-sale preparation add more on top.
Then comes the move itself. A typical local move averages around $714, a number that covers the mover but rarely the whole transition. And if you are buying as well as selling, plan on the other side of the deal too: a buyer generally pays 2 to 5 percent of the purchase price in closing costs, often including lender fees, an appraisal, title work, and more.
Add it all up, and leaving the current house is rarely as cheap as it first looks. But the money spent to leave is only half the picture, because staying carries its own price tag, and that one is much quieter.
Staying avoids all of the selling expenses, and that is exactly why it feels like the cheaper choice. But staying has its own costs, and much of them never arrive as a bill with your name on it. The long-standing rule of thumb is to budget 1 to 3 percent of a home's value every year for maintenance and repairs, before utilities, insurance, and property taxes, all of which trend upward over time. On a sizable North Shore home, that range is real money every single year.
There is also the invisible cost of a paid-off home. Equity sitting in the walls is earning nothing, while the same money conservatively invested could be generating real income each year, often tens of thousands of dollars annually on a sizable home. That is not a reason to move on its own, but it belongs in the comparison, because it quietly changes which side of the math wins.
Here is where the easy assumptions fall apart: downsizing does not automatically mean lower monthly costs. A new, smaller mortgage at today's rates can carry a higher payment than an old low-rate loan on the larger house. Plenty of owners with a low-rate mortgage on a paid-down home would be surprised at how much the monthly payment rises for a smaller property at a higher rate.
Many condo and community moves also bring HOA fees along with the smaller footprint, commonly $300 to $600 a month, before you factor in shared insurance or a special assessment that can appear. Sometimes staying is the genuinely cheaper choice, and sometimes leaving is. That is why the answer comes from working through the full comparison rather than assuming which way it goes.
The true cost comparison is exactly the kind of analysis I bring to my listing appointments and buyer consultations on the North Shore. We start with what the current home can net after the real costs of selling, then we build the other side: what the next chapter really costs, month by month and year by year, from the new payment to the HOA to the maintenance that comes with a different kind of home.
I have been licensed since 2003, I know how the North Shore towns and their markets actually work, and I will tell you what I really think, even when it is not the answer you expected. Whether you end up staying or moving, you will make the decision with the full picture in hand.
If you have been asking yourself whether staying is really the cheaper choice, that is a question worth a conversation. Reach out through the Meet with Kathleen page, or book a time that works for you, and we will look at your options together.
The total cost to sell a home in Massachusetts commonly lands around 9 to 11 percent of the sale price once commission, the deed excise tax, the attorney, and pre-sale preparation are all counted.
Staying costs more than the mortgage: budget 1 to 3 percent of a home's value every year for maintenance and repairs, before utilities, insurance, and property taxes that trend upward.
A paid-off home carries a quiet opportunity cost: equity sitting in the walls earns nothing, while conservatively invested it could generate real income every year.
Downsizing does not automatically lower monthly costs: a smaller mortgage at today's rates can cost more than an old low-rate loan, and HOA fees commonly run $300 to $600 a month.
Sometimes staying is the genuinely cheaper choice, and sometimes leaving is. The honest answer comes from comparing both sides with real numbers.
Ask Kathleen
Straight answers to the questions North Shore homeowners ask when they wonder whether staying or moving is cheaper, from the article above.
The total cost to sell commonly lands around 9 to 11 percent of the sale price once everything is counted. Real estate commission typically runs 5 to 6 percent of the sale price and is negotiable, the state deed excise tax adds $4.56 per $1,000 of sale price, a real estate attorney is required at every Massachusetts closing, and staging and pre-sale preparation add more on top. A typical local move averages around $714.
The long-standing rule of thumb is to budget 1 to 3 percent of a home's value every year for maintenance and repairs, before utilities, insurance, and property taxes, which all trend upward over time. There is also the opportunity cost of a paid-off home: equity sitting in the walls is earning nothing, while the same money conservatively invested could generate real income each year, often tens of thousands of dollars annually on a sizable home.
No. Downsizing does not automatically mean lower monthly costs. A new, smaller mortgage at today's rates can carry a higher payment than an old low-rate loan on the larger house, and many condo and community moves bring HOA fees, commonly $300 to $600 a month, along with the smaller footprint. Sometimes staying is the genuinely cheaper choice, and sometimes leaving is, which is why the full comparison matters.
Line up both sides with real numbers: what the current home would net after the full cost of selling, the true annual carrying cost of staying including maintenance, and the complete month-to-month cost of the next home, from the new mortgage payment to HOA fees to utilities. That is exactly the comparison Kathleen Militello builds at her listing appointments and buyer consultations on the North Shore.
Related topics
The honest answer lives in the full comparison, not in the assumption. You do not have to figure this out alone, and my job is to protect your interests either way. Wherever the math lands, the goal is a next chapter you feel good about long after the closing, and I would be glad to help you see it clearly.
Written by
Kathleen Militello, Realtor®
The Militello Team · eXp Realty · MA Salesperson License 9053343 · Serving Boston's Coastal North Shore
Keep reading
The true cost question is one of the most common reasons North Shore homeowners call. Bring your numbers, or just bring the question, and we will do the honest comparison together. Reach out through the Meet with Kathleen page, or book a time that works for you.
Kathleen Militello, Realtor® / The Militello Team | eXp Realty
Experience Matters.