Ask Kathleen · Downsizing on the North Shore
Does Downsizing Actually Save You Money on the North Shore?
Kathleen Militello, Realtor® · Published November 10, 2026 · Updated November 2026 · 9 min read · Boston's Coastal North Shore
Ask Kathleen · Downsizing on the North Shore
Kathleen Militello, Realtor® · Published November 10, 2026 · Updated November 2026 · 9 min read · Boston's Coastal North Shore
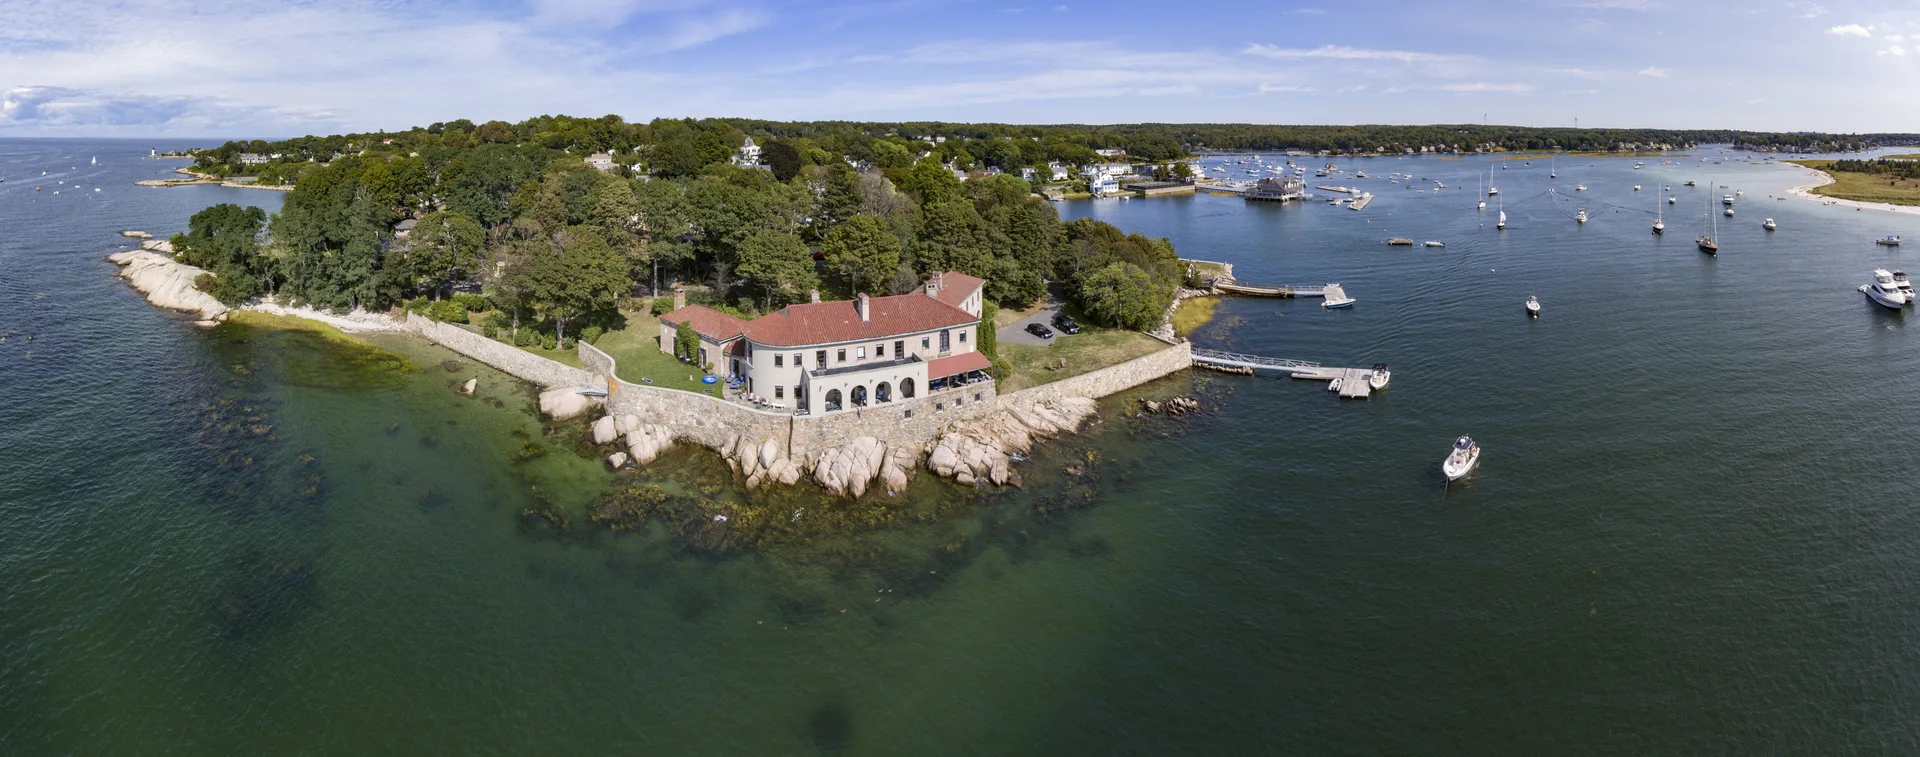
Smaller does not automatically mean cheaper. Whether downsizing actually saves you money comes down to the monthly carrying costs of the new place versus the old one, plus one tax question that most North Shore sellers never think about. Here is the honest math, the Massachusetts rules that apply, and a simple way to run your own numbers.
The first surprise for many downsizers is that a smaller home can cost more per month than the one they left. Once you add condo or HOA fees, property taxes, insurance, and utilities, the monthly line items can run higher in a two-bedroom condo than in a four-bedroom house. Full-service condo associations in Greater Boston commonly run roughly $700 to $1,500 per month, according to 2026 industry guides, and that is before the mortgage payment.
The old house has its own line items, and they are worth writing down before you compare: property taxes on a larger assessed value, heating and cooling for more square footage, insurance, and the steady drip of maintenance that every older home carries, from roof and boiler to painting and landscaping. Some of those shrink when you move, and some do not. The honest comparison is line by line, not square foot by square foot.
On the sale side, the news is usually good. The federal primary-residence exclusion, Section 121 of the tax code, shields up to $250,000 of gain for a single filer and $500,000 for married couples filing jointly, as long as you owned and lived in the home for two of the five years before the sale. Massachusetts conforms to the federal exclusion, according to the Massachusetts Department of Revenue and state tax documents, so most North Shore downsizers owe no capital gains tax on the sale.
Keep records of what you spent on permanent improvements over the years, because those dollars raise your cost basis and shrink any taxable gain. Receipts from a new roof, a kitchen renovation, or a new heating system can quietly move you further below the exclusion limits.
Here is the rule that almost nobody mentions in a downsizing conversation. Massachusetts voters passed the Fair Share Amendment in November 2022, adding a 4% surtax on taxable income above an inflation-indexed threshold. The threshold was $1,000,000 for 2023, $1,053,750 for 2024, $1,083,150 for 2025, and $1,107,750 for 2026, according to the Massachusetts Department of Revenue, and it is adjusted each year.
Two details matter. The 4% applies only to the portion of taxable income over the threshold, not to the whole gain. And there is no special home-sale exclusion from the surtax: a gain that is taxable for regular income tax is taxable for the surtax too, per Massachusetts Department of Revenue guidance as reported by tax and legal analyses.
That creates what tax planners call the one-time-sale trap. A long-held coastal home sold in a high-value year can push a filer over the line in that single year, even when every other year of their income sits far below it. The gain the federal exclusion covers is not the issue; the surtax looks at total taxable income for the year, and one large sale can change the picture.
The honest calibration: this is a planning conversation, not a scare. MassBudget, using 2021 data, found that only 895 home sales statewide could have generated a gain over $1 million after the joint-filing exclusion, and in most Massachusetts cities and towns, zero sales produced a gain over $1.5 million. Most sellers never come close to the threshold.
Here is the checklist I walk sellers through before they list. Write down the likely sale price of your home, subtract your purchase price plus documented improvements and selling costs to estimate the gain, then subtract the $250,000 or $500,000 exclusion. Add the year's other taxable income, and see where that total lands against the current surtax threshold. If it stays under the line, the surtax is not part of your move.
Do this before closing, not after. Tax planning that happens ahead of a sale has options; planning that starts after the closing is mostly paperwork. And one clear note: this is general information, not tax advice. Confirm the specifics of your situation with a CPA or tax advisor before you make decisions.
Across the North Shore, the money math turns on two things: how long you have owned the home and where it sits. A home bought decades ago in Beverly, Salem, Gloucester, or Manchester-by-the-Sea has very different gain math than one bought recently, because the appreciation happened over a different span of years. The exclusion and the surtax both start from your own purchase price, your improvements, and your filing status.
That is why the honest answer is always personal. Two similar homes in the same town can produce very different numbers for two different owners. Run the checklist with your own figures, and if the picture is not clear, that is exactly what a conversation with a CPA, a tax advisor, and a real estate professional who knows the local market is for.
Smaller does not automatically mean cheaper; the monthly line items, condo or HOA fees, taxes, insurance, and utilities, decide the real comparison.
Full-service condo associations in Greater Boston commonly run roughly $700 to $1,500 per month, according to 2026 industry guides.
The federal Section 121 exclusion shields up to $250,000 of gain for single filers and $500,000 for married couples filing jointly, and Massachusetts conforms, so most North Shore downsizers owe no capital gains tax.
Massachusetts' 4% surtax applies only to taxable income above an inflation-indexed threshold, and only to the portion over it; there is no home-sale exclusion from the surtax.
MassBudget, using 2021 data, found only 895 home sales statewide could have generated a gain over $1 million after the joint-filing exclusion; for most sellers the surtax never comes into play.
Run the checklist before closing and confirm the specifics with a CPA or tax advisor; this is general information, not tax advice.
Ask Kathleen
Straight answers to the questions North Shore homeowners ask when they wonder whether downsizing really saves money, from the article above.
Most North Shore downsizers owe no capital gains tax. The federal Section 121 exclusion shields up to $250,000 of gain for a single filer and $500,000 for married couples filing jointly, and Massachusetts conforms to the federal exclusion, according to the Massachusetts Department of Revenue. The exclusion applies when you owned and lived in the home for two of the five years before the sale.
The Fair Share Amendment, passed by Massachusetts voters in November 2022, adds a 4% surtax on taxable income above an inflation-indexed threshold. The threshold was $1,000,000 for 2023, $1,053,750 for 2024, $1,083,150 for 2025, and $1,107,750 for 2026, according to the Massachusetts Department of Revenue, and it changes each year.
It can, in one specific situation. A gain that is taxable for regular income tax is taxable for the surtax too; there is no special home-sale exclusion. But the 4% applies only to the portion of your taxable income over the threshold in that single year, and MassBudget's 2021 data found only 895 home sales statewide could have generated a gain over $1 million after the joint-filing exclusion, so most sellers never come close.
Run the checklist: estimate the sale price, subtract your purchase price, improvements, and selling costs, subtract the $250,000 or $500,000 exclusion, add the year's other taxable income, and compare the total against the current threshold. Do it before closing, and confirm the specifics with a CPA or tax advisor.
Related topics
Downsizing can save real money, and it can also cost more than staying put, depending on the monthly math and the tax picture. The way to know is to run the numbers for your own home, in your own town, before you make the call. I have walked North Shore homeowners through this comparison many times, and I will tell you what I really think. Reach out through the Meet with Kathleen page, or book a time that works for you, and we will do the honest math together.
Written by
Kathleen Militello, Realtor®
The Militello Team · eXp Realty · MA Salesperson License 9053343 · Serving Boston's Coastal North Shore
Keep reading
The money question is one of the most common reasons North Shore homeowners call, and the answer is always personal. Bring your numbers, or just bring the question, and we will do the honest comparison together. Reach out through the Meet with Kathleen page, or book a time that works for you.
Kathleen Militello, Realtor® / The Militello Team | eXp Realty
Experience Matters.