Buying Your Next Home
Love Your Mortgage Rate, but Is It Keeping You in the Wrong House?
Kathleen Militello · Published October 29, 2026 · 7 min read · Boston's Coastal North Shore
Buying Your Next Home
Kathleen Militello · Published October 29, 2026 · 7 min read · Boston's Coastal North Shore
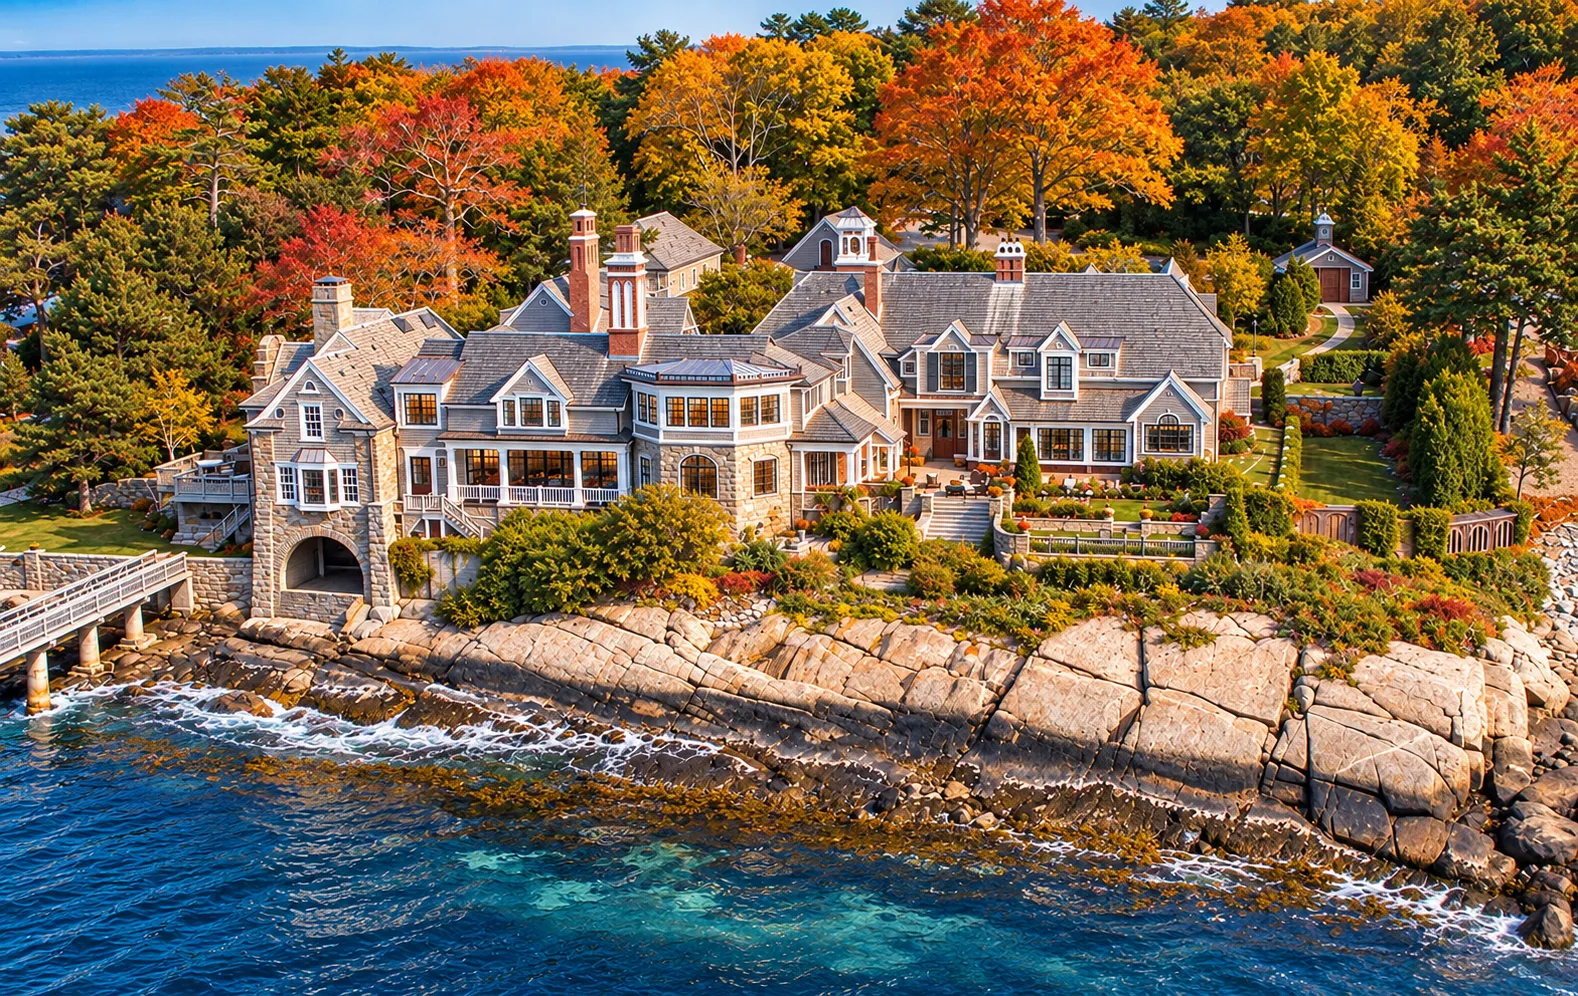
Many North Shore homeowners are sitting on a 2 to 3 percent mortgage rate from a few years ago and assume they can never move, because today's rates would raise their payment. That assumption deserves a closer look. Sometimes staying is the right call, and sometimes the low rate is quietly keeping a household in the wrong house. This post works through the decision in three parts: the rate math, the lifestyle costs, and the equity in the current home.
Start with the honest math. Compare keeping your current low-rate loan and staying put against taking out a new mortgage at today's rates and buying the home you would actually move into. The payment on a move-up purchase depends on the price, the down payment, the rate, and the property taxes, so the comparison only works when it is built on real numbers for a real next home, not on a headline rate.
A few honest ways to think about it. Your rate is one line of the budget, not the whole decision. A move-up purchase is a new mortgage, not a refinance of the old one: you are not swapping the rate on the same loan, you are borrowing for a different and usually larger home, so the payments differ in kind, not just in size. And some buyers choose to keep the old home and rent it instead of selling. That can be a sound strategy, but it is a decision to make with a lender and a tax advisor, because the loan qualification, insurance, and taxes all change.
I wrote the full cost-of-selling math in The True Cost of Staying Versus Moving, where the rough 9 to 11 percent of the sale price in Massachusetts comes from: commission, deed excise tax, attorney, and prep. Rather than repeat it all here, I will point to it. That post is the companion to this one, and the two together give you the complete picture.
Now the part that does not show up on a mortgage statement. A growing household can outgrow a layout long before the roof wears out: the bedroom that no longer works, the kitchen that cannot hold more than a few people, the office that is really the dining room. Those are not aesthetic complaints. They shape every ordinary week.
The commute is another quiet cost. If the daily drive has changed, or the walk to the train matters more than it used to, that time is paid every single week. Schools deserve the same honest look. A district that fit a few years ago may not fit the grade levels in the house now, and the neighborhood itself may have shifted, in character, in traffic, or in how close it is to the life you actually lead.
There is also the cost of delay. Putting off a move until rates fall can push the decision years down the road while the house stays the same size and the household does not. Nobody knows where rates go next. What is knowable is whether the home fits the life being lived today.
The equity lens is the one move-up buyers most often overlook. The current home's equity does not disappear when you sell. In most moves, it becomes the down payment on the next home. That is one of the quietest advantages of moving up: the equity you have already built gets reinvested in a home that fits, rather than sitting in a home that does not.
A move-up purchase builds equity in a home that fits. It is the home the household actually intends to stay in, and every payment on the place you mean to keep builds ownership in the life you are living. Meanwhile, equity held in a house that has been outgrown is still equity, but it is not working toward the next chapter.
The proceeds can also be used strategically: a larger down payment on the next home, lower financing costs, or simply breathing room in the new budget. The right structure depends on your numbers, your timeline, and your goals, which is exactly the conversation worth having before you assume the low rate decides the matter.
A 2 to 3 percent rate is one line of the budget, not the whole decision, and a move-up purchase is a new mortgage, not a refinance of the old one.
The full cost of selling in Massachusetts, roughly 9 to 11 percent of the sale price including commission, deed excise tax, attorney, and prep, is detailed in the companion post, The True Cost of Staying Versus Moving.
Staying costs that never show up on a mortgage statement: a layout the household has outgrown, a commute, schools, neighborhood fit, and the quiet cost of delaying a move that fits how life works now.
The current home's equity typically becomes the down payment on the next home, and used strategically, that equity can do more in a home that fits than in one that does not.
Staying can be the right call when the home still fits, but a low rate alone is not a reason to stay in the wrong house.
Ask Kathleen
Straight answers to the questions North Shore homeowners ask when they wonder whether their low mortgage rate is worth more than their current house, from the article above.
Not automatically, and not because of the rate alone. Compare a real payment on the next home, built on the price, the down payment, and today's rates, against everything staying costs in lifestyle and equity. A low rate only matters if the move it buys is worth it, and sometimes it is worth a higher payment to live in a home that fits.
Start with real numbers: what the current home is worth, what the equity can contribute as a down payment, and what a new mortgage would actually cost at today's rates. Add the cost-of-selling side, roughly 9 to 11 percent of the sale price in Massachusetts including commission, deed excise tax, attorney, and prep, plus the buying costs, and the picture becomes clear. A lender can run the qualification, and I can walk the whole comparison with you.
Some buyers do, and it can preserve a great rate while building rental income. It is a decision to make with a lender and a tax advisor, because keeping the home changes your loan qualification, your insurance, your taxes, and your responsibilities as a landlord. It is not the same as the single-home math, and it deserves its own careful look.
The big pieces are the selling costs on the current home, commonly around 9 to 11 percent of the sale price in Massachusetts including commission, deed excise tax, attorney, and prep, the buying costs on the next home, moving, and any immediate work the next home needs. None of that is a reason not to move; it is a reason to plan the move with the whole budget in view.
Related topics
low mortgage rate move up ·giving up a low mortgage rate ·golden handcuffs mortgage rate ·true cost of staying versus moving ·move-up buyer mortgage rate ·home equity down payment next home ·sell current home buy next home ·north shore move-up buyers ·kathleen militello realtor ·the militello team
Written by
Kathleen Militello, Realtor®
The Militello Team · eXp Realty · MA Salesperson License 9053343 · Serving Boston's Coastal North Shore
Keep reading
The low-rate question is really a bigger question: does this house still fit the life you are living? I have walked this exact decision with North Shore homeowners, and I will tell you what I really think. Bring your numbers, or just bring the question, and we will compare staying versus moving honestly and without pressure. Let's talk about what makes sense for you.
You don't have to figure this out alone. If the house fits, your rate is a good reason to stay. If it does not, the rate is one line of a budget that deserves the full picture.
Kathleen Militello, Realtor® / The Militello Team | eXp Realty
Experience Matters.